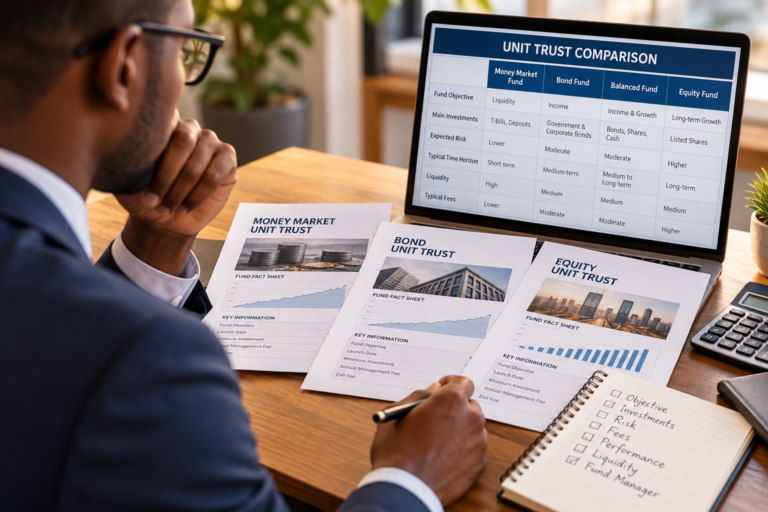


A unit trust fund fact sheet can contain some of the most useful information
available to an investor.
Unfortunately, many investors look at only one number:
the return.
A good fund fact sheet should tell you much more than how the fund performed recently.
It can help you understand what the fund owns, what it is designed to do,
how risky it may be, what it costs and whether it fits your financial goal.
If you are new to unit trusts, start with our
Unit Trusts in Zambia guide
before analysing individual fund fact sheets.
The purpose of a fund fact sheet is not simply to tell you what a fund earned.
It should help you understand what you are actually investing in.
1. Start with the investment objective
The investment objective tells you what the fund is designed to achieve.
This is the first section you should read because it helps answer a basic question:
What is this fund trying to do?
A fund may aim to:
- preserve capital;
- provide liquidity;
- generate regular income;
- invest primarily in fixed-income securities;
- deliver long-term capital growth; or
- provide exposure to equities or foreign-currency assets.
The investment objective should be compared with your own financial objective.
A fund designed for long-term capital growth may not be appropriate for money
you expect to need in a few months.
The investment vehicle should serve the financial goal, not the other way around.
2. Identify the fund type
Next, identify the type of unit trust you are reviewing.
Common categories include:
- money-market funds;
- fixed-income or bond funds;
- balanced funds;
- equity funds; and
- foreign-currency funds.
The fund type gives you an initial indication of how the fund may behave.
However, do not stop at the label.
Two funds in the same broad category may still have very different portfolios,
risk levels, fees and investment approaches.
3. Study the asset allocation
Asset allocation is one of the most important parts of the fact sheet.
It shows where the fund’s money is invested.
You may see allocations to:
- Treasury bills;
- Government bonds;
- corporate debt;
- bank deposits;
- listed shares;
- cash;
- foreign securities; or
- other permitted investments.
This tells you far more about risk than the fund name alone.
For example, a fund may be called a balanced fund, but its actual asset allocation
may show a strong concentration in one type of investment.
Always ask:
What does this fund actually own?
4. Review the top holdings
Some fund fact sheets show the largest individual investments held by the fund.
This section can help you identify concentration risk.
If a large share of the fund is invested in only a few securities, institutions
or sectors, the performance of those holdings may have a significant effect
on the overall fund.
Concentration does not automatically make a fund unsuitable, but it is something
an investor should understand.
5. Examine historical performance carefully
This is often the section investors look at first.
A fact sheet may show performance over periods such as:
- one month;
- three months;
- year to date;
- one year;
- three years;
- five years; or
- since inception.
Do not treat all of these figures as equally meaningful.
Ask:
- Is the return cumulative or annualised?
- Is it before or after fees?
- Does it include distributions?
- What period does it cover?
- How has the fund performed during weaker market periods?
- Is the comparison being made against an appropriate benchmark?
Historical returns are evidence of what happened before, not a promise
of what will happen next.
6. Understand the benchmark
Some funds compare their performance with a benchmark.
A benchmark provides a reference point against which the fund’s performance
can be considered.
The important question is not simply whether the fund beat the benchmark
during one period.
Ask whether:
- the benchmark is appropriate for the fund;
- performance is consistent over relevant periods;
- the fund took substantially more risk to achieve the result; and
- fees have been reflected in the performance shown.
7. Find the fees and charges
Fees reduce the return you ultimately receive.
A fact sheet may disclose some charges, but you should confirm whether
additional fees apply.
These may include:
- annual management fees;
- initial or entry fees;
- administration fees;
- advisory charges;
- performance fees;
- exit charges; or
- other transaction-related costs.
If the fee information is not clear, ask the fund manager for a complete
explanation before investing.
A useful comparison is not simply:
Which fund had the highest gross return?
It is:
What return remains after the relevant fees and charges?
8. Check the minimum investment
The fact sheet may state the minimum amount required to start investing.
It may also show:
- minimum additional contributions;
- minimum monthly contributions;
- minimum balance requirements; or
- different minimums for different investor types.
Affordability matters, but it should not determine the investment decision by itself.
A fund with a low minimum contribution is not automatically suitable for your goal.
9. Understand liquidity and withdrawals
A fact sheet may explain how quickly investors can redeem their units.
Look for information on:
- redemption procedures;
- notice periods;
- settlement time;
- minimum holding periods;
- withdrawal restrictions;
- exit charges; and
- minimum remaining balances.
This information is particularly important when your investment has a specific
target date.
A fund may have attractive historical returns but still be unsuitable if you cannot
access your money when you need it.
10. Read the risk information
Risk information should never be treated as a formality.
Depending on what the fund owns, risks may include:
- market risk;
- interest-rate risk;
- credit or default risk;
- liquidity risk;
- currency risk;
- concentration risk; and
- inflation risk.
Terms such as low risk should not be interpreted as
no risk.
Ask what could cause the fund’s value or income to decline.
Do not read one fund fact sheet in isolation
A fund fact sheet becomes much more useful when compared with fact sheets
from other funds serving a similar purpose.
If you are considering several unit trusts, compare them using the same criteria.
| Item to compare | Fund A | Fund B | Fund C |
|---|---|---|---|
| Fund type | |||
| Investment objective | |||
| Asset allocation | |||
| Top holdings | |||
| Minimum investment | |||
| Annual management fee | |||
| Withdrawal period | |||
| Historical performance | |||
| Main risks |
The most important question on the fact sheet
After reviewing objectives, holdings, returns, fees and risk, come back
to the question that matters most:
Does this fund help me reach my financial goal?
A fund can have strong historical performance and still be inappropriate
for what you are trying to accomplish.
Investment selection should therefore come after planning.
The fund is the vehicle.
The goal is the destination.
Continue learning about Unit Trusts
Learn how to analyse Unit Trusts in practice
Join the next weekly Unit Trusts class and learn how to read fund fact sheets,
compare fund managers, understand fees and returns, assess risk and connect
a unit trust to your investment goal.